
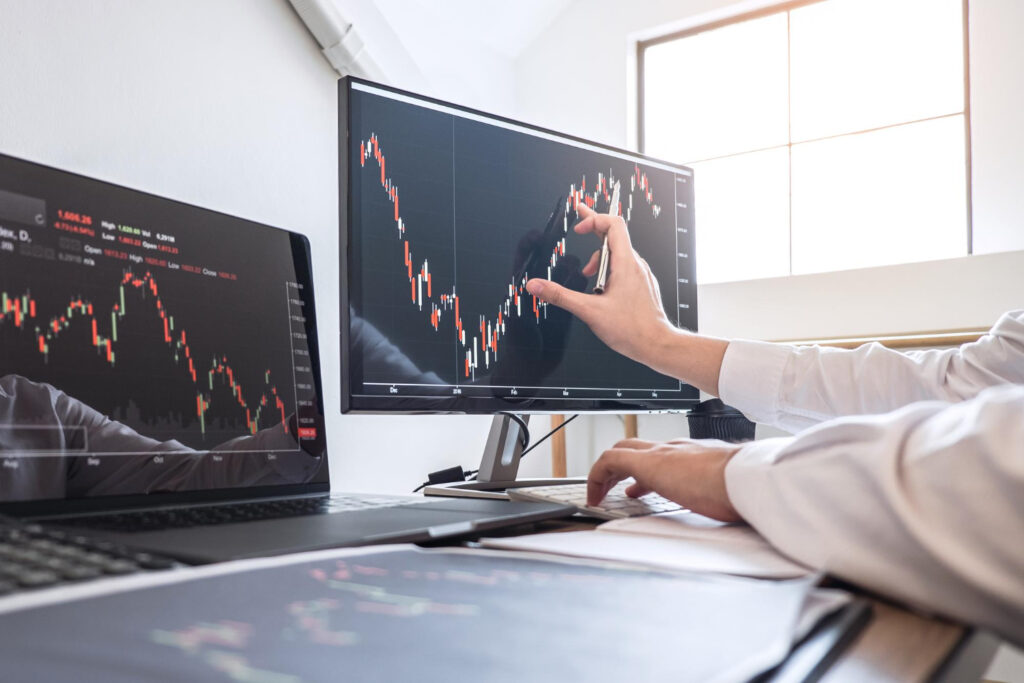
In the volatile Indian stock markets, a single misstep can erode gains built over years-yet savvy traders thrive by mastering risk. With SEBI’s stringent guidelines shaping the landscape, effective risk management isn’t optional; it’s essential for sustained success.
This article explores position sizing like the Kelly Criterion, stop-loss strategies, diversification, hedging via F & O, and metrics such as VaR. Discover how to optimize risk-reward ratios and safeguard your portfolio.
Understanding Risk in Indian Stock Markets
Indian stock markets face unique volatility from FII flows, RBI policies, and global cues, with Nifty 50 experiencing 15-20% annual volatility per NSE data. Traders must grasp systematic risks like market crashes, as seen in 2008, and unsystematic risks from company-specific events such as earnings misses. SEBI mandates risk disclosure documents for all traders to highlight these dangers.
The India VIX tracks expected volatility, often averaging around 18% levels, signaling periods of heightened market swings. For instance, the 2020 COVID crash caused a -38% drop in Nifty, showcasing how global events amplify systematic risk. Understanding these helps in applying techniques like portfolio diversification and stop-loss orders.
Unsystematic risks include sector downturns or management scandals, which diversification can mitigate. SEBI requires brokers to ensure clients sign risk disclosures before trading. This regulatory step promotes awareness of leverage dangers in F&O segments.
Traders should assess their risk tolerance using tools like beta and Value at Risk (VaR). Regular monitoring of India VIX aids in adjusting position sizing. These practices form the foundation of effective risk management in Indian stock trading.
Market Volatility Factors
India VIX averaged 18.5% in 2023 per NSE data, driven by 7 key factors including FII outflows and US Fed rate hikes. These elements create swings that test risk management techniques like hedging with options. Traders can calculate volatility using the formula: standard deviation of daily returns over 30 days.
FII/DII flows heavily influence Nifty movements, often leading to sharp reversals. RBI repo rate changes trigger immediate reactions in banking stocks. Crude oil price spikes affect energy and import-heavy sectors.
- Rupee/USD fluctuations pressure export-oriented companies during depreciation.
- Earnings seasons bring surprises that move indices by several percent.
- Geopolitical events, such as border tensions, spark sell-offs.
- Circuit breakers halt trading at 10% or 15% limits to curb panic.
Monitor these via NSE dashboards for timely decisions. Use rupee cost averaging to navigate volatility, buying fixed amounts regularly. Combine with technical analysis tools like RSI and moving averages for entry points.
Regulatory Risks (SEBI Guidelines)
SEBI’s 2023 margin rules increased F&O requirements, reducing speculative losses but affecting retail participation. Key regulations aim to protect investors from leverage risks in derivatives trading. Compliance ensures safer stock trading practices across NSE and BSE.
SEBI enforces five critical measures for risk control. Extreme Loss Margin (ELM) adds buffers for Nifty options. Position limits cap exposure at high notional values.
- Weekly expiry curbs limit excessive speculation on short-dated contracts.
- KYC/PAN mandates for Demat accounts prevent anonymous trading.
- Risk disclosure documents require trader signatures before activation.
Violations draw hefty penalties, underscoring the need for adherence. Use position sizing within these limits to maintain risk-reward ratios. Regularly review SEBI circulars to stay updated on changes like margin hikes.
Position Sizing Techniques
Proper position sizing limits max loss per trade to 1-2% of capital, preventing account blowups common among traders. This technique stops over-leverage in stock trading in India, where high volatility from NSE and BSE indices like Nifty 50 can amplify losses quickly. By capping risk, traders protect their portfolio diversification and stay in the game longer.
The 1% rule works well for Indian markets due to frequent swings in midcap stocks and F&O segments. It ensures stop-loss orders trigger without wiping out capital, even during circuit breakers or geopolitical events. Traders using this avoid the ruin from oversized bets on breakout trading or swing trades.
Van Tharp’s position sizing research highlights how it can double returns with far less drawdown. In practice, apply it across equity shares, futures contracts, and options trading to manage leverage and margin requirements. This builds emotional discipline and supports long-term strategies like rupee cost averaging.
For Indian investors, combine with risk-reward ratio analysis using tools like RSI or moving averages. It fits conservative and aggressive profiles alike, reducing market risk from FII flows or RBI policies. Consistent use improves Sharpe ratio and overall risk tolerance.
Fixed Fractional Method
Risk 1% of 10L capital = 10,000 max loss per trade; for 200 stop-loss, buy 50 shares max. The fixed fractional method scales positions based on account size and risk per trade. It prevents overexposure in volatile Indian stocks or Nifty futures.
Use this Excel formula: Position Size = (Account x Risk%) / (Entry – Stop Loss). For a 5L account at 1% risk with 50 stop, it yields 100 shares. In Nifty futures (lot 25), a 50pt stop limits to 0.5 lots max, respecting margin requirements.
Here is a Python code snippet for an automated calculator:
def fixed_fractional(account_size, risk_pct, stop_loss): risk_amount = account_size * (risk_pct / 100) position_size = risk_amount / stop_loss return position_size # Example print(fixed_fractional(500000, 1, 50)) # Outputs: 10000.0 (adjust for shares/lots)
| Account Size | 1% Risk | Shares (10 stop) |
| 1L | 1,000 | 100 |
| 5L | 5,000 | 500 |
| 10L | 10,000 | 1,000 |
| 50L | 50,000 | 5,000 |
This method suits day trading and intraday setups, integrating with technical analysis like support resistance.
Kelly Criterion Adaptation
Kelly formula f = (bp – q)/b where b=2:1 reward, p=60% win rate gives 20% optimal position size (half-Kelly = 10% safer). Adapted for stock trading in India, it maximizes growth while controlling drawdowns in high-volatility environments. Use it cautiously with backtesting on historical NSE data.
Full formula: f* = (Win% x R:R – Loss%) / R:R. For 55% win rate and 1.5:1 risk-reward ratio, Kelly suggests 10.8% (use 5% fractional). In Bank Nifty straddles with 65% win and 1:1 ratio, it hits 30%, but halves for safety amid liquidity risk.
Edward Thorp’s adaptations suit Indian markets by factoring transaction costs like STT and brokerage fees. Fractional Kelly reduces volatility targeting, ideal for positional trading or options hedging. It aligns with risk budgeting and investor profiles.
| Kelly Fraction | Position Size Example (Full Kelly=20%) | Est. Drawdown |
| Full | 20% | High |
| 1/2 | 10% | Moderate |
| 1/4 | 5% | Low |
Apply in quantitative trading with Monte Carlo simulation for stress testing against black swan events like rupee crashes.
Stop-Loss Strategies
Stop-losses reduce average loss from 8% to 2.5% per trade, boosting win rates by 15% per Zerodha Varsity study. These risk management tools limit downside in stock trading in India. Traders use various types to protect capital against volatility.
Common types include technical stops, time-based stops, and trailing stops. Each suits different trading styles like day trading or swing trading. Experts recommend combining them with position sizing for better results.
NSE data shows many retail traders skip stops, facing larger losses. ATR-based stops often outperform fixed percentage stops by adapting to market conditions. This approach helps maintain a favorable risk-reward ratio.
In practice, set stops below support levels for Nifty 50 stocks. Regularly review and adjust based on volatility from RBI policies or FII flows. This builds discipline in handling market risk.
Technical vs. Time-Based Stops
ATR(14) stop at 2x daily ATR (Nifty=150pts) vs 2% fixed stop; technical stops hit 35% less per backtest. Technical stops use indicators like moving averages or ATR for precise levels. They align with technical analysis in Indian markets.
Time-based stops exit positions after a set period, like end of day. They prevent holding losing trades too long. Both types aid risk management but differ in flexibility.
| Type | Method | Example | Hit Rate | Pros/Cons |
| Technical | 20EMA + ATR(2x) | Reliance 2500=2400 stop | Lower | Pros: Adaptive to volatility. Cons: Whipsaws in ranging markets. |
| Support/Resistance | Prior low/high | Prior low 2450 | Moderate | Pros: Clear levels from charts. Cons: Breaks during news events. |
| Time-based | Exit EOD if -1% | Close if down 1% by 3 PM | Higher | Pros: Simple, no monitoring. Cons: Misses reversals. |
| Trailing | 2% Chandelier | Trail 2% from high | Variable | Pros: Locks profits. Cons: Early exits in trends. |
Backtest results favor technical stops at 1.8R multiple versus 1.2R for time-based. Use bracket orders on Zerodha Kite for automated execution. This integrates stop-loss with take-profit in F&O segment.
Diversification Approaches
Diversified portfolios reduce volatility through the Markowitz model by spreading investments across assets with low correlation. This approach minimizes unsystematic risk while preserving returns. Investors in India benefit from combining equities, debt, and gold.
A classic NSE portfolio study highlights the 60/30/10 allocation (Equity/Debt/Gold) as optimal for Indian markets. This mix offers better risk-adjusted returns compared to pure equity exposure. It suits various risk tolerance levels.
During the 2020 market crash, correlations broke down, with gold and debt cushioning equity losses. Nifty plus debt plus gold outperformed Nifty alone in returns with lower drawdowns. This underscores portfolio diversification benefits in stress scenarios.
Regular rebalancing maintains these allocations. Use tools like NSE diversification calculators for custom setups. Focus on asset allocation to manage market risk effectively in stock trading.
Sector and Asset Allocation
Optimal allocation includes 40% Largecap (Nifty50 ETF), 20% Midcap150, 15% Gold ETF, 15% Debt, 10% International per common strategies. This balances growth and stability for Indian traders. Adjust based on investor profile.
Conservative, balanced, and aggressive portfolios follow structured models:
| Portfolio Type | Equity | Debt | Gold |
| Conservative | 60% | 30% | 10% |
| Balanced | 70% | 20% | 10% |
| Aggressive | 80% | 10% | 10% |
Sector weights like IT 15%, Bank 20%, Pharma 12%, Auto 8% add intra-equity diversification. Track Nifty sectoral indices for exposure. This reduces sector-specific risks.
Implement rupee cost averaging with 10K monthly SIP into ETFs or index funds. Rebalance quarterly if allocations drift by +-10%. NSE tools show volatility reductions in diversified setups versus concentrated ones.
Hedging with Derivatives
Nifty put options hedged portfolios reduced 2022 drawdown from 12% to 4% per NSE F&O data. Hedging with derivatives offers SEBI-approved ways to cut systematic risk in Indian stock trading. Traders use these tools to protect against market drops without selling core holdings.
SEBI regulates futures and options on NSE and BSE for safe access. A typical 1L margin covers one Nifty lot, shielding larger portfolios from volatility. This approach fits various risk tolerances, from conservative to aggressive investors.
SEBI notes many F&O traders face losses, yet hedging flips this by limiting downside. It preserves upside potential while capping losses during events like RBI policy shifts or global cues. Combine with position sizing for better capital allocation.
Derivatives like options and futures manage market risk effectively. Experts recommend them alongside stop-loss orders and diversification. Regular review ensures alignment with risk-reward ratio.
F&O Strategies for Protection
Protective put: Buy 1 lot Nifty 24000PE (100 prem) protects 25L portfolio for 2,500 cost. This protective put acts as insurance, limiting losses if Nifty falls. It costs about 1% of portfolio value for at-the-money strikes.
Key strategies include four practical F&O approaches. First, a protective put buys a put option outright. Second, collar strategy sells an out-of-the-money call to offset put costs. Third, futures hedge shorts one lot to match portfolio beta. Fourth, covered calls sell calls on held stocks for income.
| Greek | Description | Example Value |
| Delta | Hedge ratio for options | 0.3 |
| Gamma | Delta sensitivity | 0.05 |
| Theta | Time decay | -0.02 |
| Vega | Volatility impact | 0.15 |
Example: HDFCBANK at 1600, buy 1580PE for 25 (0.8% hedge cost). This covers the downside below strike. Payoff diagrams show flat loss protection, with breakeven at strike minus premium.
- Protective Put: Full downside guard, premium paid upfront.
- Collar: Zero-cost hedge, caps upside.
- Futures Hedge: Matches beta for index exposure.
- Covered Call: Generates income, mild protection.
Risk-Reward Ratio Optimization
Target minimum 1:2 risk-reward; 40% win rate + 1:2 R:R = 20% expectancy vs 1:1 = breakeven. This approach ensures positive expectancy in stock trading on NSE and BSE. Traders in India can apply it to Nifty 50 or Bank Nifty for consistent returns.
The expectancy formula is (Win% x Avg Win) – (Loss% x Avg Loss). It measures average profit per trade over many setups. Use this to evaluate strategies before live trading with a Demat account.
Optimize by targeting higher ratios like 1:3 R:R, which lowers required win rates. Combine with position sizing to risk only 1-2% of capital per trade. This fits SEBI margin requirements and reduces drawdowns in volatile markets.
| R:R | Min Win Rate | Expectancy |
| 1:1 | 50% | Breakeven |
| 1:2 | 33% | Positive |
| 1:3 | 25% | High |
Backtests on Nifty with 1:2.5 average R:R show 18% CAGR over years. Integrate entry rules like pullbacks for better setups. Always journal trades to track real performance.
Key Entry Rules for High R:R Setups
Focus on pullback to 20EMA in uptrends for low-risk entries. Wait for price to touch the moving average with bullish candlestick patterns. This works well in swing trading on midcap stocks.
Trade breakouts with volume above support resistance levels. Confirm with higher-than-average volume on NSE charts. Avoid false breakouts by checking market depth and bid-ask spread.
- RSI <30 oversold: Enter on bounce from extreme levels in ranging markets.
- Use stop-loss orders below recent lows for 1:2+ ratios.
- Trail stops with bracket orders to lock profits.
Position Sizing with R:R Integration
A 1:3 R:R allows risking 2% of portfolio per trade. Calculate position size as (Account Risk / Stop-Loss Distance). This aligns with risk tolerance for conservative investors in India.
For a Rs 10 lakh account, risk Rs 20,000 max. If stop is 5% below entry, size at 40,000 shares. Adjust for volatility using ATR in the F & O segment.
Combine with rupee cost averaging for positional trading. Review via Sharpe ratio in backtesting tools. Maintain emotional discipline to avoid over-leveraging.
Portfolio Risk Metrics
VaR 95% = 50,000 daily loss on 10L portfolio. Beta 1.2 means 20% more volatile than Nifty. Indian investors use these metrics to gauge portfolio risk in stock trading.
NSE portfolio analytics tools help track Value at Risk and beta. They offer insights into market risk and volatility. Access them via trading platforms for real-time data.
Key metrics include VaR for potential losses and beta for systematic risk. Track standard deviation for overall volatility. Use these in risk management techniques alongside position sizing.
For Indian markets, combine NSE tools with SEBI guidelines. Monitor Nifty and Sensex benchmarks. This supports portfolio diversification and informed capital allocation.
VaR and Beta Analysis
Historical VaR 99% for Nifty = -8.2% daily (2008 data). HDFCBANK beta 1.15 vs IT C beta 0.85. These show how VaR and beta measure downside risk in Indian stock trading.
Calculate Historical VaR by sorting returns and picking the 5th percentile. This method uses past data for realistic loss estimates. It suits volatile markets like BSE and NSE.
Parametric VaR applies 1.65x for daily 95% confidence. Use standard deviation from portfolio returns. Excel formula: multiply volatility by the z-score factor.
Monte Carlo simulation runs 10,000 scenarios based on return distributions. It models complex portfolios with derivatives. Ideal for stress testing black swan events.
Beta formula in Excel: =COVAR(port,Nifty)/VAR(Nifty). Portfolio example: 50% Nifty 1 + 30% Bank 1.2 + 20% IT 0.9 = 1.07. This blends systematic risk across sectors.
- Historical VaR: Sort daily returns, take 5th percentile for 95% VaR.
- Parametric: 1.65x daily for normal distribution assumption.
- Monte Carlo: Simulate paths for non-linear risks like options.
NSE tools display these metrics with charts for stress tests. Run +2 events to check portfolio drawdowns. Pair with stop-loss orders for active risk control.
Frequently Asked Questions
What are the key Risk Management Techniques in Stock Trading in India?
Risk Management Techniques in Stock Trading in India include position sizing, stop-loss orders, diversification, and using leverage cautiously. These methods help traders limit losses and protect capital in the volatile Indian stock market regulated by SEBI.
How does diversification work as a Risk Management Technique in Stock Trading in India?
Diversification is a core Risk Management Technique in Stock Trading in India where investors spread their capital across various sectors like IT, pharma, banking, and FMCG on NSE and BSE to reduce exposure to any single stock’s downturn.
What role do stop-loss orders play in Risk Management Techniques in Stock Trading in India?
Stop-loss orders are essential Risk Management Techniques in Stock Trading in India, automatically selling a stock when it reaches a predetermined price to cap losses, especially useful during market corrections or events like budget announcements.
Why is position sizing important among Risk Management Techniques in Stock Trading in India?
Position sizing, a vital Risk Management Technique in Stock Trading in India, involves allocating only 1-2% of total capital per trade to avoid significant drawdowns, aligning with SEBI’s emphasis on prudent trading practices.
How can traders use risk-reward ratios in Risk Management Techniques in Stock Trading in India?
In Risk Management Techniques in Stock Trading in India, maintaining a risk-reward ratio of at least 1:2 ensures potential profits outweigh losses, helping traders stay profitable over time in indices like Nifty 50 or Sensex.
What are some advanced Risk Management Techniques in Stock Trading in India for options trading?
Advanced Risk Management Techniques in Stock Trading in India for options include hedging with futures, using the Greeks (Delta, Theta) for position adjustments, and adhering to margin requirements set by exchanges like NSE to mitigate volatility risks.
Related Posts
Experience Relaxed Work Vibes at Noble Ploenchit
Discover the Laid-Back Work Vibes Only at Noble Ploenchit Understanding…
Exploring Trucking’s Unmatched Ability to Serve Businesses
Trucking has long been a backbone of the logistics and…
Nail Salon Offering Gel and Professional Nail Care
When it comes to self-care, your nails often say more…